Introduction: The Invisible Multi-Month Journey to a Closed Deal
Marketing within the financial services sector has always operated under a distinct and unforgiving set of constraints. Unlike fast-moving e-commerce environments or high-velocity Software-as-a-Service (SaaS) transactions where conversions often follow a linear, easily traceable path, financial services operate on a vastly different timeline. In this landscape, the educational white paper downloaded in early spring and the ink drying on a multi-million-dollar institutional agreement in late autumn can be separated by months of deliberation, stakeholder shifts, and rigorous internal debate.
This temporal and structural chasm is where standard return on investment (ROI) reporting routinely fails. Traditional marketing analytics tools, built primarily for immediate gratification and short-tail conversions, struggle to quantify the long-term impact of enterprise content. For marketing leaders in banking, wealth management, insurance, and fintech, this creates a chronic justification problem: how do you prove the commercial value of foundational content when it plays out across complex sales cycles and large, fragmented buying committees?
To answer this, modern financial marketers must move past the simplistic comfort of last-touch attribution. They need to understand why traditional ROI metrics break down in long-cycle environments, how modern buying groups actually make decisions, and what alternative frameworks look like when tailored to satisfy the scrutiny of a Chief Financial Officer.
Main Facts: The Structural Disconnect in Financial Services Attribution
The fundamental challenge of measuring financial services content marketing lies in a structural mismatch between how tracking tools collect data and how enterprise buyers make purchasing decisions.
In a standard B2B transaction—and particularly within high-stakes financial environments—a buyer’s journey is rarely a solitary endeavor. According to industry data, B2B buying groups typically range from five to 16 individuals, drawing across as many as four distinct corporate functions. In a financial services context, these groups routinely include a Chief Financial Officer (CFO), a corporate controller, compliance officers, risk management leads, and operational analysts.
Each of these stakeholders approaches the buying process through a unique lens. The risk officer focuses on regulatory exposure and security; the controller zeroes in on upfront costs and amortization schedules; the analyst examines day-to-day usability; and the CFO evaluates the overall capital allocation efficiency and projected payback period. Consequently, these individuals consume different pieces of content, at different times, for entirely different reasons.
Furthermore, much of this content consumption occurs anonymously or off-platform. Research highlights that a substantial majority of modern B2B buyers prefer a rep-free buying experience, conducting extensive independent research, peer consultations, and self-directed searches long before they ever fill out a contact form or speak with a sales representative.
When a deal eventually closes, standard attribution models often attribute 100% of the conversion credit to whatever asset happened to be open in the browser during the final signature—frequently a product landing page, a pricing calculator, or a direct sales demo request. The foundational thought leadership, the regulatory compliance guides, and the early-stage exploratory research that genuinely shaped the committee’s consensus months prior receive zero credit. This systemic flaw distorts marketing budgets, undervalues brand-building content, and leaves marketing teams struggling to defend their strategic value to executive leadership.
Chronology: Mapping the Anatomy of a Long-Cycle Financial Deal
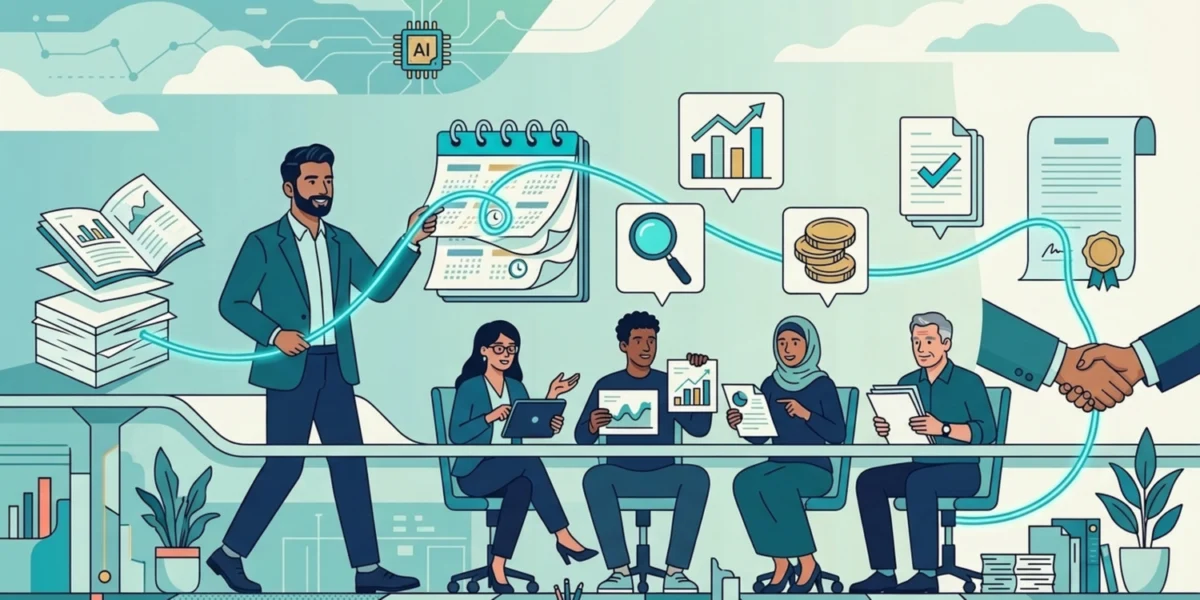
To fully grasp why conventional measurement models fail, it is helpful to trace the chronological evolution of a typical enterprise financial services sales cycle. By breaking down the timeline, marketing leaders can pinpoint precisely where standard analytics lose the thread.
Phase 1: The Self-Directed Discovery (Months 1–3)
The journey often begins quietly. A mid-market financial institution or enterprise corporate treasury faces a structural inefficiency—perhaps cross-border payment bottlenecks or shifting regulatory reporting requirements.
- The Action: The initial researcher (often an analyst or mid-level manager) conducts anonymous Google searches, reads industry research reports, and downloads foundational white papers or analytical toolkits.
- The Measurement Reality: Because this interaction happens anonymously, it may register merely as unassigned web traffic. If a form is filled out, it generates a single early-stage lead record, but the true intent behind the search remains obscured.
Phase 2: Internal Consensus Building and Conflict (Months 4–6)
As the problem gains visibility, the buying group expands. The initial researcher brings findings to departmental heads. However, alignment is rarely instantaneous. Industry surveys indicate that an overwhelming majority (74%) of B2B buying teams experience internal friction and conflict during the decision-making process, often driven by competing departmental goals.
- The Action: During this phase, stakeholders consume targeted content designed to mitigate risk, clarify compliance mandates, or demonstrate operational efficiency. They share analytical frameworks, case studies, and business-case calculators internally.
- The Measurement Reality: This content sharing frequently occurs via direct downloads, email forwarding, or offline discussions. Traditional CRM systems and web analytics tools fail to capture these internal handoffs, rendering this crucial phase invisible to standard tracking.
Phase 3: Formal Evaluation and Risk Assessment (Months 7–9)
The committee narrows its options down to a shortlist. Risk officers and compliance teams step in to vet potential vendors thoroughly.
- The Action: Stakeholders review technical documentation, security white papers, and integration guides. Sales calls and formal vendor presentations take place.
- The Measurement Reality: Marketing begins to regain visibility here as prospects interact with specific product pages, request demos, and engage directly with sales enablement materials.
Phase 4: Procurement and Final Sign-Off (Months 10–12)
The deal reaches the procurement and executive approval stage. The CFO and controller review the financial terms, pricing models, and projected ROI.
- The Action: Contract negotiations conclude, legal teams clear final terms, and the agreement is executed.
- The Measurement Reality: Standard last-touch attribution swoops in, assigning all marketing credit to the final asset accessed just before contract execution—completely ignoring the foundational work performed during the previous three phases.
Supporting Data: What the Research Tells Us
The structural challenges of financial services marketing are well-documented across multiple industry studies and institutional surveys. Understanding these data points provides the necessary context for overhauling corporate measurement strategies:
- Expanding Buying Committees: According to recent sales surveys conducted by Gartner, B2B buying groups routinely comprise 5 to 16 individuals spanning up to four distinct operational functions. In financial services, where regulatory and fiduciary oversight is paramount, this committee size often skews toward the higher end of the spectrum.
- Internal Friction: Gartner’s research also reveals that 74% of B2B buying teams demonstrate unhealthy conflict during their decision-making process. This underscores the vital role that educational and consensus-building content plays in resolving strategic stalemates early in the sales cycle.
- The Self-Directed Buyer: Up to 61% of B2B buyers express a clear preference for a rep-free buying experience, conducting the majority of their vendor evaluation independently through digital channels before ever engaging a sales representative.
- Lengthening Sales Cycles: Data compiled in global sales reports indicates that 57% of sales professionals report lengthening sales cycles, driven by economic caution, increased risk aversion, and more rigorous internal procurement gates.
These statistics collectively paint a clear picture: as financial sales cycles lengthen and buying committees grow more insular and complex, relying on superficial conversion metrics is no longer a viable option for marketing executives.
Official Perspectives and Industry Responses
As the limitations of last-touch attribution become increasingly apparent, marketing and sales leadership across the financial sector are actively rethinking how value is quantified. Industry analysts, compliance directors, and content strategists are advocating for a structural shift in how marketing performance is evaluated.
According to marketing analytics specialists in the B2B space, the obsession with immediate lead generation has historically forced financial brands to underinvest in top-of-funnel educational content. "When a marketing team is judged solely on the volume of immediate form fills, they naturally gravitate toward tactical, low-value bottom-of-funnel offers," notes a senior B2B content strategist. "In finance, that approach completely ignores how enterprise buyers actually buy. You cannot rush a CFO or a risk committee with a gated checklist."
Regulatory compliance experts also weigh heavily on this discussion. In heavily regulated sectors such as banking, wealth management, and securities, every piece of content must pass stringent internal review boards and adhere to strict regulatory guidelines (such as FINRA or SEC standards). Because producing compliant, authoritative thought leadership requires significant investment in expert writing—frequently involving Chartered Financial Analysts (CFAs), Juris Doctors (JDs), and registered reviewers—treating this content as disposable or failing to measure its true commercial impact creates friction between marketing budgets and executive finance teams.
Consequently, modern financial institutions are pivoting toward holistic, account-based measurement frameworks that treat content not as a direct lead-generation trap, but as an institutional asset capable of influencing complex buying groups over extended time horizons.
Implications: Building a Better Measurement Model for Financial Services
Transitioning away from flawed attribution models requires deliberate operational changes. To accurately capture the true business impact of financial services marketing, organizations must implement a multi-stakeholder, full-journey measurement framework.
1. Shift from Lead-Centric to Account-Based Tracking
Because financial sales cycles involve large committees, tracking individual leads in isolation is insufficient. Organizations must adopt account-based marketing (ABM) analytics platforms that aggregate engagement data at the account or buying-group level. By tracking how multiple individuals within the same target institution interact with content over time, marketers can build a comprehensive picture of account momentum.
2. Implement Weighted Multi-Touch Attribution
Discarding last-touch and first-touch models in favor of custom, weighted multi-touch attribution allows marketing teams to distribute credit fairly across the entire journey. Under this model, early-stage educational resources, mid-stage risk guides, and late-stage product comparisons all receive proportional credit based on their empirical influence on closed-won deals.
3. Focus on Metrics That Matter to a CFO
To earn and maintain the trust of executive leadership, financial marketers must translate marketing output into the language of the boardroom. Key performance indicators should move beyond vanity metrics like page views and raw lead volume, focusing instead on:
- Content-Influenced Pipeline: Measuring the total monetary value of sales opportunities that have engaged with specific content assets.
- Influenced Revenue: Connecting closed-won revenue directly to accounts that consumed targeted content during their evaluation cycle.
- Buying-Group Reach: Quantifying how many distinct functions (e.g., risk, finance, compliance, operations) within a target account have engaged with marketing materials.
- Cycle-Time Impact: Analyzing whether accounts that deeply engage with educational content progress through the sales pipeline faster than those that do not.
4. Bridge the Gap Between Sales and Marketing
No measurement model can succeed without strict alignment between sales and marketing teams. Both departments must agree on a unified attribution framework and definitions before reporting numbers upstream. Routine alignment meetings ensure that intent signals captured by marketing are effectively handed off to sales, and that qualitative insights from sales calls are fed back into content strategy.
Conclusion
Marketing in the financial services sector is an exercise in patience, precision, and regulatory rigor. While the gap between initial content engagement and the final closing bell can stretch across many months and involve dozens of stakeholders, that gap does not excuse inaccurate measurement.
By abandoning outdated attribution models and embracing multi-stakeholder, account-level frameworks, financial institutions can finally illuminate the hidden phases of their sales cycles. When marketing teams begin measuring what truly matters—influenced revenue, buying-group reach, and pipeline velocity—they align their reporting with the strategic metrics that CFOs already use to evaluate every other enterprise investment. In doing so, they secure not only a clearer picture of content ROI, but also a more influential seat at the executive table.