NEW YORK — In the high-stakes world of financial services marketing, a quiet frustration pervades executive boardrooms and marketing departments alike. The distance between the piece of content that sparks a deal and the actual ink drying on a contract can span three quarters, or even a full year.
This temporal gulf is where standard return on investment (ROI) reporting routinely collapses. In an industry defined by complex regulatory frameworks, multi-million-dollar transactions, and notoriously conservative buyers, traditional attribution models are no longer just inadequate—they are actively misleading.
As financial institutions face lengthening sales cycles and increasingly fragmented buying committees, industry leaders are grappling with a fundamental paradigm shift: moving away from simplistic, conversion-centric metrics toward sophisticated, multi-stakeholder attribution models that mirror the reality of modern enterprise finance.
The Anatomy of the Measurement Gap
To understand why traditional marketing analytics fail in the financial sector, one must examine the typical, circuitous journey of an enterprise finance buyer.
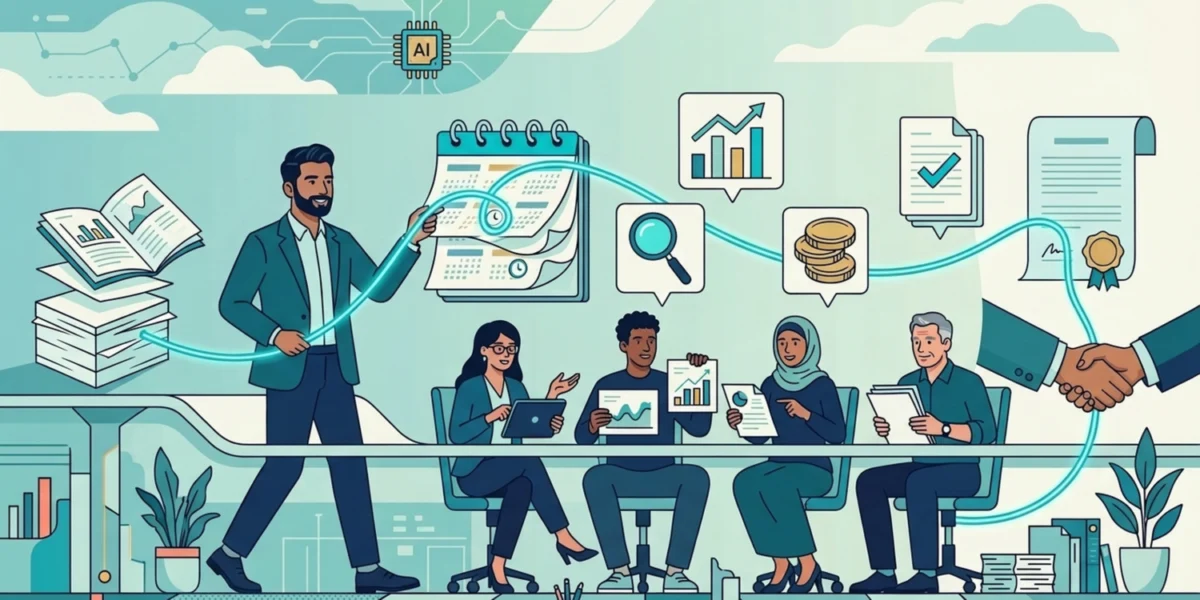
Consider a hypothetical scenario: A director of risk management at a mid-market wealth management firm downloads a white paper analyzing regulatory compliance trends in March. The document is read, filed away, and seemingly forgotten. Over the next eight months, the deal winds its way through a labyrinthine corporate structure. A procurement lead, a compliance officer, two financial analysts, and the Chief Financial Officer (CFO) each weigh in on the software or service under review. When the contract finally executes in November, that original white paper is never once mentioned on a sales call.
When revenue is ultimately recognized, attribution platforms face an impossible question: Which touchpoint actually influenced the deal?
For institutions marketing financial services, this question frequently lacks a definitive answer. Standard attribution tools—which are heavily optimized for fast-moving B2B software-as-a-service (SaaS) or direct-to-consumer retail—exacerbate the confusion.
The core issue is structural. Long sales cycles and sprawling buying committees inherently divorce content engagement from the moment of conversion. Last-touch reporting, which automatically assigns 100% of the credit to the final URL a user visited before filling out a form, routinely credits whatever webpage happened to be open in the browser at the moment of signing. To measure content ROI effectively in finance, organizations must abandon last-touch attribution in favor of multi-stakeholder models that reflect the collective nature of enterprise buying decisions.
Chronology of a Complex Sale: From Spark to Signature
To map out why simple ROI math fails in financial services, it is helpful to trace the chronological evolution of a modern finance sale.
Phase 1: The Self-Directed Discovery (Months 1–2)
Long before a lead form is ever populated, potential buyers are conducting independent research. According to data from Gartner, approximately 61% of B2B buyers now prefer a completely rep-free buying experience during the early stages of evaluation. In finance, this often involves anonymous browsing of white papers, tax calculators, and regulatory guides. Early-stage content deployed here plays a monumental role in shaping category perception, yet it leaves virtually no trace in standard CRM systems.
Phase 2: Internal Alignment and Committee Formation (Months 3–5)
Once an initiative gains internal momentum, the buying group expands. Research from Gartner indicates that typical B2B buying groups range from five to 16 people across as many as four distinct corporate functions. In finance, this group invariably includes a CFO or controller whose fiscal criteria diverge sharply from those of an operational accountant or a compliance officer.
Furthermore, these groups rarely move in harmonious lockstep. Gartner’s sales surveys reveal that an alarming 74% of B2B buying teams experience tangible conflict during the decision-making process, with stakeholders frequently operating under competing internal goals. Content that helps resolve these cross-functional conflicts early in the cycle can save a deal from stalling, yet it rarely registers on lead-generation dashboards.
Phase 3: The Evaluation and Procurement Gauntlet (Months 6–8)
As the shortlist narrows, security reviews, legal evaluations, and risk assessments take center stage. Content consumed during this phase tends to be highly technical—implementation guides, security audits, and total-cost-of-ownership (TCO) models.
Phase 4: The Close and the Attribution Fallacy (Month 9+)
The deal closes. The CRM registers a closed-won opportunity, and leadership demands an accounting of marketing’s contribution. Because last-touch models dominate legacy systems, the entire multi-month, multi-stakeholder journey is flattened into a single data point: a webinar registration from week two, or a pricing-page visit from the day before signing.
As enterprise finance deals stretch across the calendar, this disconnect widens. Compounding the challenge, 57% of sales professionals report that sales cycles are actively getting longer, according to data compiled by Salesforce. Linking a single piece of content to revenue becomes mathematically untenable when a committee of up to 16 people takes nearly a year to reach a consensus.
Supporting Data and Industry Insights
The structural flaws of traditional financial marketing metrics are underscored by hard data from leading market research firms and industry analysts.
- The Multi-Person Committee Reality: Gartner’s sales surveys consistently highlight that enterprise purchases are collaborative, committee-driven undertakings. With buying groups averaging 5 to 16 stakeholders, relying on a single lead score or individual contact history is fundamentally flawed.
- Internal Friction: The 74% conflict rate among buying teams emphasizes that financial buyers are not just looking for product features; they are seeking risk mitigation and internal consensus-building tools.
- The Lengthening Sales Horizon: Salesforce data indicating that 57% of sales cycles are lengthening means that attribution windows must expand accordingly. A 30-day attribution window is practically useless when enterprise sales routinely exceed 180 to 360 days.
- The Rise of Off-Platform Research: Because buyers conduct the vast majority of their research independently—often via third-party publications, peer networks, and un-gated resources—marketers must look beyond owned properties to understand true market influence.
Official Responses and Industry Perspectives
Marketing executives and compliance specialists within the financial services sector are increasingly vocal about the need for a total overhaul of measurement standards.
"For years, financial services marketing has been caught in a trap of its own making," notes Sarah Jenkins, a B2B enterprise marketing strategist specializing in wealth tech and banking. "We use fast-cycle metrics to measure slow-cycle enterprise sales. When the board asks what the marketing budget actually returned, we hand them lead counts and cost-per-acquisition metrics that completely miss the fact that our content successfully navigated a risk committee of twelve people."
Compliance officers also play an unusual, stabilizing role in this ecosystem. Unlike traditional tech sectors where rapid iteration is championed, financial marketing must navigate stringent regulatory bodies such as FINRA, the SEC, and various global banking authorities.
"When you have CFAs, JDs, and FINRA-registered reviewers vetting every piece of educational content before it goes live, the production cost and strategic weight of that asset are vastly higher than a standard blog post," explains David Vance, a managing director at a compliance-first financial advisory firm. "If you invest that heavily in high-integrity content, evaluating it solely on immediate form fills is a strategic failure. You need a measurement model that respects the long-tail authority those assets build."
Implications for Financial Services Marketing Strategy
To survive and thrive in an environment of extended sales cycles and hyper-cautious buying committees, financial institutions must systematically overhaul their measurement infrastructure, executive reporting, and content strategies.
1. Shift from Leads to Account-Level Influence
Because finance purchases are group decisions, individual lead-based scoring is obsolete. Marketers must aggregate engagement data at the account or buying-group level. If three different stakeholders from the same prospective bank download three distinct research reports over four months, that account is signaling high intent—even if none of them filled out a bottom-of-the-funnel "Contact Sales" form.
2. Redefine Metrics to Resonate with the CFO
CFOs and controllers do not evaluate capital investments based on page views or click-through rates. To secure and expand marketing budgets, financial marketers must adopt financial-grade metrics:
- Content-Influenced Pipeline: Measuring the total volume of pipeline value that has interacted with marketing assets across the buying journey.
- Influenced Revenue: Tying closed-won revenue back to accounts that engaged with specific thought leadership or educational programs.
- Buying-Group Reach: Assessing whether content is successfully penetrating multiple functional areas (e.g., reaching both the risk officer and the CFO) within target accounts.
- Cycle-Time Impact: Evaluating whether accounts that deeply engage with specific educational content close faster than those that do not.
- Engagement Quality Over Quantity: Valuing ten meaningful minutes spent interacting with an advanced interactive business-case calculator far above a thousand anonymous, fleeting page views.
3. Build a Full-Journey Measurement Framework
Bridging the measurement gap requires triangulating multiple data streams. Because no single tool can capture the entire off-platform and on-platform journey, marketing teams must synthesize CRM data, web analytics, and third-party intent signals to approximate the hidden phases of the sales cycle. Furthermore, sales and marketing leadership must reach a strict, upfront consensus on the chosen attribution model before reporting results to the executive suite, ensuring internal alignment when deals finally close.
Conclusion: Aligning Measurement with Reality
The challenge facing financial services marketers is formidable, but it is not insurmountable. By moving past the seductive simplicity of last-touch attribution and embracing account-level, multi-stakeholder measurement frameworks, financial institutions can finally bridge the gap between early-stage content engagement and late-stage revenue generation.
In an industry where trust, regulatory compliance, and rigorous financial analysis dictate every business decision, marketing measurement must evolve to match the sophistication of the buyers it serves. When marketing is measured in terms of influenced revenue, buying-group reach, and cycle-time compression, it ceases to be viewed as a cost center—and rightfully takes its place as a predictable, high-value engine for enterprise growth.