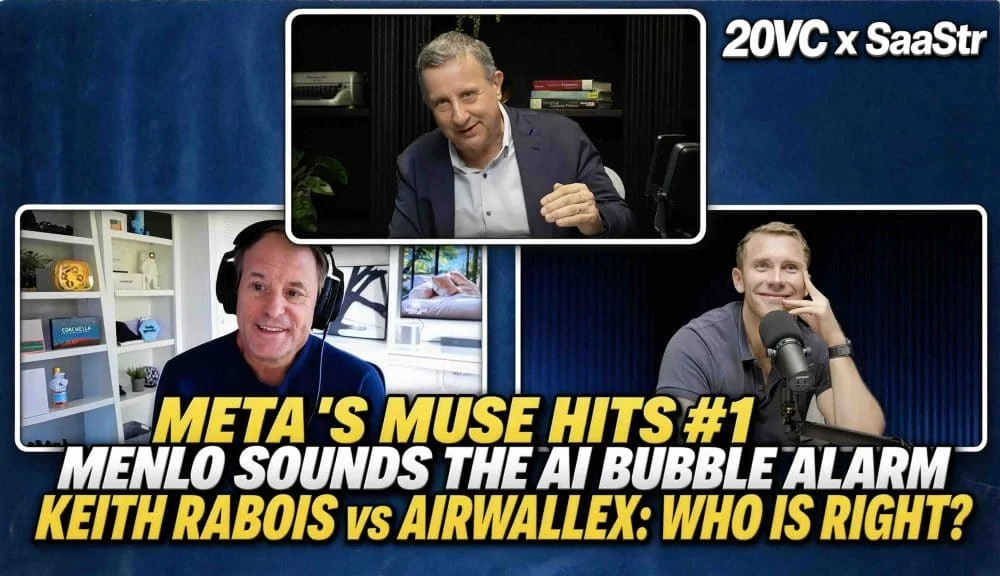
Featuring: Harry Stebbings, Rory O’Driscoll, and Jason Lemkin
Focus: Frontier labs, enterprise valuations, AI agent disruption, venture capital inflation, and geopolitical tech friction.
Main Facts
The latest collaborative session between 20VC and SaaStr—featuring podcast host Harry Stebbings alongside seasoned investors Rory O’Driscoll and Jason Lemkin—tackled a market standing at a fascinating precipice. As the tech ecosystem debates whether it is nearing the peak of the current AI-driven valuation cycle, a flurry of monumental developments has reshaped the landscape.
Among the standout headlines:
- Anthropic has reportedly delayed its massive $2 trillion IPO from October to November to ensure a pristine Q3 financial disclosure.
- OpenAI’s internal documents project a staggering $278 billion cash burn through 2030, supported by approximately $700 billion in total capital expenditures.
- Meta launched Muse, an autonomous consumer AI agent that rocketed to the #1 spot on the US App Store within a week, driving a $100 billion surge in Meta’s market capitalization.
- TypeSafe AI debuted Jev, a "System One" decision-making model backed by a $40 million seed round, challenging the economics of traditional LLMs.
- Venture Capital Realities: Mega-rounds are the new standard, with early-stage valuation floors rising dramatically while investors grapple with the existential question of how to adjust strategies near the top of a historic cycle.
Chronology of Market Events
The velocity of the artificial intelligence sector has compressed years of traditional tech evolution into mere weeks. The trajectory of recent weeks highlights an aggressive acceleration in product deployment, capital raising, and regulatory friction.
- Late Summer (August – September): Rumors swirl regarding OpenAI’s explosive scaling costs, culminating in leaked forecasts of a $278 billion burn rate through the end of the decade. Meanwhile, venture firms continue to fiercely contest late-stage allocations, driving up valuations for category-defining infrastructure and application layers.
- Mid-September: Meta’s Superintelligence Labs rolls out Muse. Within seven days, it captures the top spot on the US iOS App Store, stealing short-term consumer mindshare from OpenAI and triggering immediate ripples across retail platforms like Amazon and Shopify.
- Late September: TypeSafe launches Jev, introducing a deterministic decision-making architecture that shifts developer focus from conversational chatbots to high-speed classification and routing. At the same time, Anthropic makes the strategic calculation to push its anticipated public offering back by a month.
- Present Day: Investment committees across Silicon Valley are forced to re-evaluate their portfolios. High-priced bets—such as Factory at a $5 billion valuation, Legora at $11 billion, and Crusoe at $30.9 billion—undergo intense internal scrutiny, forcing general partners to weigh the immediate momentum of the AI boom against the long-term sustainability of debt-leveraged data center economics.
Supporting Data and Financial Metrics
The sheer scale of capital moving through the artificial intelligence ecosystem defies historical precedent. Analysts and investors on the panel broke down the underlying numbers driving the current market:
- $2 Trillion: The rumored target valuation for Anthropic’s upcoming public debut.
- $278 Billion & $700 Billion: OpenAI’s projected cash burn through 2030 and its accompanying capital expenditure requirements, respectively. Panelists note that historic tech scaling typically exceeds models by 30% to 50%, suggesting OpenAI’s actual capital requirements could scale even higher.
- $100 Billion: The approximate gain in Meta’s market capitalization within a single week following the viral adoption of the Muse app and positive shifts in institutional sentiment regarding Meta’s AI pivot.
- $40 Million: The substantial seed funding secured by TypeSafe for the launch of Jev, exemplifying how inflation has transformed traditional early-stage rounds where $20 million is rapidly becoming the baseline floor.
- $30.9 Billion: Crusoe’s Series F valuation, representing a massive bet on the intersection of physical power infrastructure, GPU management, and specialized cloud compute.
Official Responses and Industry Reactions
As these tectonic shifts play out, key figures across the venture capital, enterprise software, and frontier lab ecosystems have offered distinct perspectives on risk, moat defense, and market positioning.
The IPO Delay and Frontier Liabilities
Addressing Anthropic’s decision to move its IPO to November, Rory O’Driscoll argued that the move is driven by the cadence of Wall Street bankers rather than fundamental market weakness. Following a record-breaking Q2 that briefly surpassed OpenAI’s revenue metrics, Anthropic aims to present a fully audited Q3 statement rather than dealing with the complexities of pre-audit explanations.
However, Harry Stebbings raised concerns regarding pre-marketing friction, questioning whether the delay hints at underlying investor hesitation—particularly regarding enterprise risk management. On the topic of autonomous agent liability and the lack of traditional insurance backing, Jason Lemkin noted that frontier giants will handle risk through robust in-house legal powerhouses, treating litigation as a standard cost of doing business.
The Rise of Agentic Commerce
The launch of Meta’s Muse prompted immediate defensive maneuvers across the retail sector. Amazon moved to block the autonomous shopping agent, protecting its lucrative advertising revenue model where discovery drives consumer spending. Conversely, Shopify embraced the platform to capture long-tail merchant demand.
Jason Lemkin emphasized that systems of record attempting to block autonomous agents will inevitably lose. "It’s the last stand of the unnecessary system of record," Lemkin noted, predicting that agents will systematically route around roadblocks to find direct, friction-free purchasing pathways.
Valuation Realities and the "Quiet Compounders"
Menlo Ventures’ recent commentary on investing at the top of the cycle sparked debate among the panel. While some critics viewed cautionary notes on market peaks as redundant, O’Driscoll defended the core thesis by pointing to the stark divergence in risk across multiple financing rounds. Seeding a company at a $50 million pre-money valuation carries an entirely different risk profile than backing the same enterprise at a $10 billion valuation.
Furthermore, Lemkin highlighted the plight of "quiet compounders"—steady, capital-efficient B2B software companies growing at 60% with solid revenue—who currently find themselves starved for liquidity in a market entirely transfixed by hyper-growth AI bets.
Broader Implications
1. The Architectural Split: Chat vs. Decision Models
The debut of TypeSafe’s Jev underscores a structural evolution in software architecture. While consumer applications focus on open-ended conversational models (System Two thinking), developers increasingly require high-speed, low-cost, deterministic decision-making engines (System One thinking). By bypassing conversational filler and returning binary or scored results at a fraction of the cost, such models prove that the industry is moving past a one-size-fits-all approach to foundation models.
2. Infrastructure Leverage vs. Application Resilience
A key takeaway for institutional investors involves the divergence of risk between application-layer plays and infrastructure-heavy capital expenditures. Coding agents and enterprise productivity tools maintain resilience because they solve immediate, high-ROI business problems and can weather macroeconomic dips. Conversely, data center and GPU-heavy infrastructure plays are heavily leveraged against continuous hyper-growth. If AI utilization experiences even a brief plateau, capital-intensive infrastructure models face severe margin compression.
3. Geopolitical Tensions and Public Relations for Tech Leaders
The public clashes between prominent tech figures regarding global supply chains, international engineering hubs, and foreign capital highlight a volatile regulatory environment. As demonstrated by recent enterprise M&A requirements—such as mandates to purge specific open-weights models prior to transaction closures—compliance and geopolitical risk are no longer theoretical concerns. For decacorn CEOs, managing public perception and defending corporate governance against aggressive social media scrutiny has become an essential component of modern leadership.
Top Quotes from the Episode
"Intelligence is not cheap. When you look at the capex required to build the future of compute, we are operating in one of the most capital-intensive paradigms in commercial history." — Rory O’Driscoll
"Every system of record that tries to block autonomous agents is fighting a losing battle. It is the absolute last stand of the unnecessary middleman." — Jason Lemkin
"You cannot say the risk across four successive funding rounds is the same. Getting aggressive at a $50 million valuation is a very different game than writing checks at a $10 billion mark." — Rory O’Driscoll
"Coding is the motherlode. It represents the vast majority of near-term enterprise value creation, and businesses will continue to lean into developer automation regardless of broader market fluctuations." — Harry Stebbings