Retail media has cemented its status as the darling of modern digital marketing. From Amazon Sponsored Products to bespoke ad units launched by legacy grocery chains and fashion marketplaces, advertising published directly on retail platforms has evolved into a dominant revenue stream. Industry projections underscore this meteoric rise: a landmark 2025 study published in the Journal of Retailing estimated global retail media spending at an astonishing $140 billion for 2024, which included a robust $54 billion in the United States alone. More recent forecasts from eMarketer project that U.S. retail media ad spending will surge to $69.33 billion by 2026, representing a massive 17.9% year-over-year increase from 2025.
Yet, beneath the glossy headline figures and explosive growth charts lies a complex economic dilemma. While retail media networks (RMNs) generate billions for the platforms hosting them, their actual impact on both brands (advertisers) and retailers (publishers) is far more nuanced than standard vanity metrics suggest. Increasingly, industry experts, economists, and brand executives are asking a critical question: Does retail media consistently create new economic value, or is it merely shifting profit margins around within a closed ecosystem?
Main Facts: Deconstructing the Retail Media Engine
At its core, retail media refers to advertisements placed on digital storefronts, apps, and owned channels by the retailers themselves. To understand the ecosystem, it helps to look at the dual role many ecommerce companies play:
- As Advertisers: A merchant selling products through marketplaces like Amazon, Walmart, or Target can purchase sponsored placements to capture high-intent shoppers.
- As Publishers: That exact same merchant may also operate its own ecommerce site and email lists, selling ad inventory to its own suppliers and third-party brands.
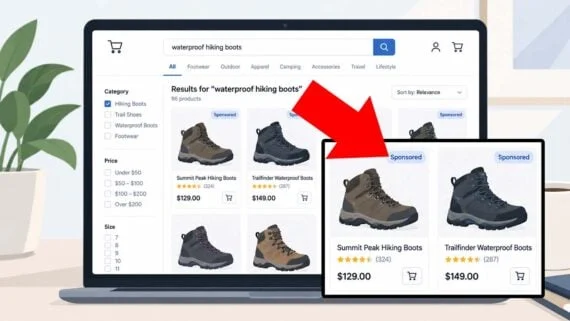
The primary allure of retail media for brands is proximity to the point of purchase. Traditional digital advertising, such as social media ads or search engine optimization (SEO), often intercepts consumers higher in the funnel when they are merely browsing or researching. Retail media, by contrast, targets consumers at the bottom of the funnel. When a shopper searches an ecommerce platform for “waterproof hiking boots,” their purchase intent is immediate and explicit.
However, the foundational premise of retail media is value creation through incremental demand. If an ad campaign generates sales that would not have happened otherwise, it succeeds. If it merely taxes transactions that would have occurred naturally, it becomes an expensive tollbooth rather than a growth engine.
Chronology: The Evolution of Retail Media from Niche Feature to Mainstream Juggernaut
To grasp how retail media reached its current crossroads, it is vital to trace its development over the past decade:
- Phase 1: The Search-Driven Genesis (Mid-2010s): Early retail media was largely synonymous with marketplace sponsored listings, pioneered by Amazon. Brands quickly realized that bidding on keyword terms within a marketplace could protect their market share from competitors and boost visibility.
- Phase 2: The Data Gold Rush and First-Party Cookies (Late 2010s to 2020): As privacy regulations (such as GDPR and CCPA) tightened and tech giants began phasing out third-party cookies, retailers sat on a goldmine: authenticated, deterministic first-party purchase data. Brands shifted budgets away from open-web programmatic advertising toward walled-garden retail networks to leverage shopper data.
- Phase 3: The Omnichannel Explosion (2021–2024): Retail media networks expanded rapidly beyond native digital storefronts. Traditional brick-and-mortar giants—including grocery chains, home improvement stores, and pharmacies—built out in-store digital screens, loyalty app programs, and connected TV (CTV) networks, transforming every customer touchpoint into potential ad inventory.
- Phase 4: The Performance Reckoning (2025–Present): As retail media budgets consume larger portions of marketing allocations, financial analysts, brand executives, and academic researchers have begun scrutinizing the actual net returns of these campaigns. The 2025 Journal of Retailing study marked a turning point by formally addressing the risk of margin erosion and non-incremental spending.
Supporting Data: The Economics of Incremental vs. Non-Incremental Spend
The true economic value of retail media depends entirely on whether a sale is incremental. Consider two distinct financial scenarios for a brand advertising on an ecommerce marketplace:
Scenario A: True Value Creation (Incremental Sales)
- Ad Spend: $1,000
- Attributed Revenue: $5,000 (sales that would not have occurred without the ad)
- Contribution Margin (Before Ad Cost): $1,500
- Net Benefit: $500 profit after subtracting ad spend.
In this scenario, the retail media campaign successfully generated new demand, expanding the pie for both the brand and the marketplace.
Scenario B: Margin Erosion (Non-Incremental Sales)
- The Situation: A seller historically ranks high organically for its core product categories on a major marketplace.
- The Platform Shift: The marketplace introduces more sponsored placements, pushing organic results further down the page. Competitors begin aggressively bidding on those slots.
- The Result: To maintain a $50 sale that it previously captured organically without any ad expense, the seller is forced to spend $5 on advertising.
In Scenario B, the marketplace generates $5 in ad revenue, but the brand’s net profitability declines. The ad spend acted as a tax on pre-existing organic visibility rather than a generator of new revenue. The Journal of Retailing paper highlighted this exact phenomenon as a primary concern for modern advertisers, noting that high Return on Ad Spend (ROAS) figures often mask the reality of non-incremental spending.
Official Responses and Industry Perspectives
As the limitations and risks of retail media come to light, leaders across the digital commerce landscape are adjusting their perspectives.
The Brand Perspective: Moving Beyond ROAS
Chief Marketing Officers and ecommerce directors are increasingly pushing back against traditional performance metrics. For years, agencies and platforms justified budgets using Return on Ad Spend (ROAS) multipliers (e.g., "$8 in sales for every $1 spent"). However, savvy advertisers now recognize that a high ROAS can be entirely illusory if those customers would have purchased anyway.
Major consumer packaged goods (CPG) brands are deploying sophisticated measurement techniques to separate true incrementality from correlation. Large enterprises now routinely use randomized holdout experiments, geo-testing (comparing ad-heavy regions to un-targeted control regions), and advanced marketing mix models. Smaller companies, lacking massive data science teams, are shifting toward analyzing baseline organic performance periods, tracking new-customer acquisition ratios, and pausing campaigns periodically to measure organic drop-off.
The Retailer Perspective: Balancing Ad Revenue and Customer Experience
Retailer-publishers face their own delicate balancing act. On paper, monetizing website real estate through supplier ads looks like pure profit.
Consider a retail category page generating $100,000 in monthly merchandise sales and $30,000 in gross profit. A major supplier agrees to pay $3,000 per month for a prominent sponsored product placement. At first glance, total margin appears to climb to $33,000.
However, if that sponsored placement displaces the retailer’s own high-margin conversions or promotes a competing product that pulls share away from more profitable private-label goods, organic gross profit might fall from $30,000 to $28,000. In this case, the retailer collected $3,000 in media revenue but only gained $1,000 overall. If product sales drop further to $26,000, the $3,000 in ad revenue actually lowered overall gross profit by $1,000. Advertising revenue increased, but overall business performance declined.
Beyond immediate margin calculations, retailer-publishers face long-term risks regarding customer experience. Flooding a site with too many sponsored products, irrelevant recommendations, or cluttered ad banners can degrade site usability. If shoppers find it harder to discover what they are looking for, customer trust erodes, long-term loyalty drops, and overall site conversion rates suffer.
Implications: The Future of the Retail Media Landscape
The retail media market is far too large and strategic to fade away, but its next phase of evolution will require greater transparency, better measurement tools, and a realignment of incentives between brands and retailers.
- Demand for Third-Party Verification: Just as programmatic display advertising had to mature with viewability standards and third-party fraud verification, retail media networks will face increasing pressure to offer independent attribution measurement. Advertisers will no longer accept black-box data directly from the platforms selling the ads.
- Refined Ad Inventory Design: Successful retailers will carefully curate their ad placements to ensure they complement, rather than cannibalize, organic search results and user experience. Over-monetizing digital storefronts will become a recognized liability for long-term customer retention.
- Strategic Alignment: Retailers and suppliers must move away from zero-sum budget negotiations. Collaborative planning—where retail media dollars are tied directly to joint business planning, product innovation, and true market expansion—will separate winning retail media ecosystems from those that merely squeeze brand margins.
Conclusion
Retail media is neither a guaranteed win nor an inherent loss. For advertisers, it is a powerful growth tool only when it generates profitable, incremental demand. For retailers, it is a viable revenue stream only when media gains outweigh any erosion of core product margins. As the market matures past its initial hyper-growth phase, distinguishing between true value creation and expensive margin redistribution will define the success of brands and platforms alike.