Main Facts
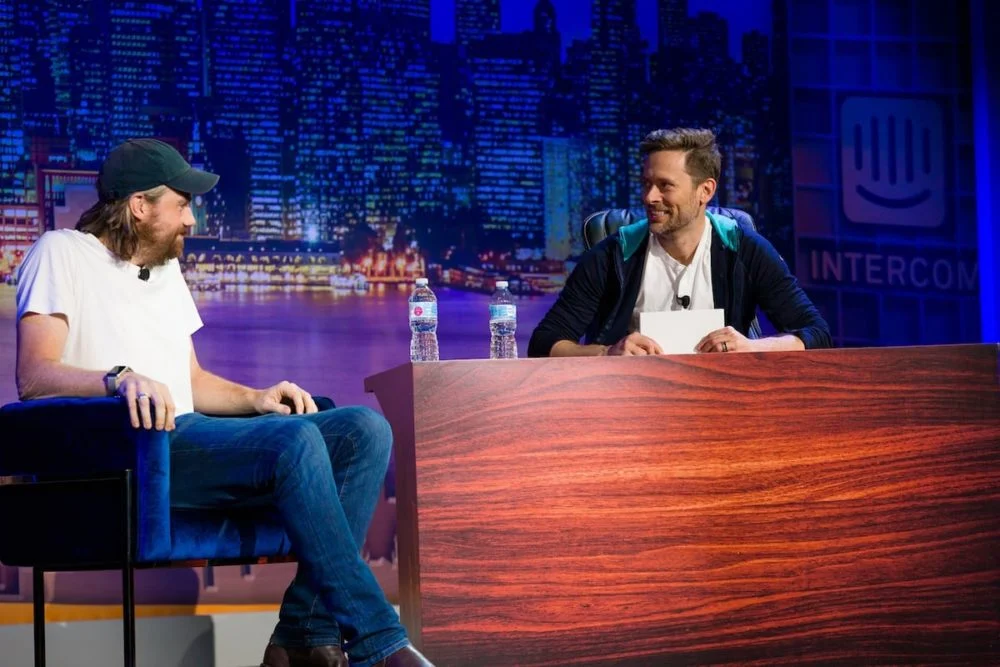
The debate over when—or even if—a startup should seek outside funding remains one of the most polarizing topics in the modern entrepreneurial ecosystem. Addressing this dilemma in a recent advisory session, SaaStr founder Jason Lemkin tackled a fundamental question frequently posed by early-stage founders: “If you started a new company today, how long would you be bootstrapped for before seeking funding?”
Lemkin’s core thesis offers a counter-narrative to the prevailing "move fast and raise big" mentality that has dominated Silicon Valley for the past two decades. According to Lemkin, if a founder possesses the luxury of choice and has access to seed capital, they should carefully evaluate three critical operational questions before taking external money. If the startup can answer "Yes" to all three, Lemkin argues that delaying or entirely bypassing outside capital is the superior strategic path.
By bootstrapping longer, founders can avoid the debilitating dilution of equity that comes with early-stage financing rounds. This approach mirrors the historic trajectories of massive software enterprises like Atlassian and Qualtrics. These companies famously resisted heavy venture backing in their early years, choosing instead to bootstrap until they achieved undeniable product-market fit and "escape velocity." When they finally did raise institutional money, it was at eye-watering, nine-figure valuations—and often strictly for secondary share sales, allowing early employees and founders to cash out rather than funding day-to-day operations.
While icons of efficiency like Zapier and Calendly accepted minimal early funding (often just a small seed round) before scaling into profitable unicorns, Lemkin acknowledges that the vast majority of unicorns still follow the traditional path of raising multiple successive venture rounds. Nevertheless, the strategic advantage of retaining control, preserving equity, and proving unit economics organically remains an elite playbook for capital-efficient growth.
Chronology
To understand the evolution of the bootstrap-versus-fund debate, it is essential to trace how startup financing models have shifted over the last twenty years:
- The Pre-Cloud Era (Late 1990s – Early 2000s): Building software required massive capital expenditures in on-premise servers, hardware, and extensive IT infrastructure. Bootstrapping a tech company was exceedingly difficult, making venture capital a mandatory prerequisite for almost any ambitious software venture.
- The SaaS Revolution and Cloud Computing (Mid-to-Late 2000s): The advent of AWS, open-source software, and modern web frameworks drastically lowered the cost of starting a software company. Pioneers like Atlassian (founded in 2002) capitalized on this shift, bootstrapping operations entirely from customer revenue and growing sustainably without institutional capital.
- The Hyper-Funding Boom (2010s – 2021): Fueled by historically low interest rates and a massive influx of venture capital, the startup ecosystem shifted toward a "growth-at-all-costs" mindset. Raising large seed rounds and Series A capital became a status symbol, leading many founders to dilute their equity early, sometimes before establishing a reliable business model.
- The Capital Correction (2022 – Present): Following macroeconomic tightening, rising interest rates, and a sharp contraction in venture capital deployment, the pendulum swung back. Investors and founders alike rediscovered the virtues of capital efficiency, unit economics, and extended bootstrapping. Conversations around sustainable growth—akin to Lemkin’s modern philosophy—returned to the forefront of entrepreneurial strategy.
Supporting Data and Industry Benchmarks
While the allure of bootstrapping is strong, empirical data from the venture capital and SaaS ecosystems reveals a nuanced picture of how modern companies scale:
- The Dilution Reality: Founders who raise capital across multiple early rounds (Pre-Seed, Seed, Series A, Series B) frequently find their ownership stakes diluted to the single digits or low teens by the time the company reaches a liquidity event. Conversely, bootstrapped founders retain significantly larger equity slices, translating to exponentially higher net worths upon acquisition or IPO.
- The Unicorn Exception vs. Rule: Data analytics of tech unicorns show that while companies like Atlassian and Qualtrics reached hundreds of millions in revenue with zero or minimal primary venture capital, over 85% of modern unicorns raise three or more rounds of institutional funding before hitting a $1 billion valuation.
- Capital Efficiency Metrics: Top-tier B2B SaaS companies typically aim for a "Magic Number" (sales efficiency metric) above 0.75 and a Rule of 40 score (growth rate plus profit margin) that exceeds 40%. Bootstrapped companies that master these unit economics early are often besieged by venture capitalists offering high valuations on founder-friendly terms, completely inverting the traditional power dynamic.
Official Responses and Expert Perspectives
The philosophy of delayed fundraising has garnered substantial commentary from industry veterans, venture capitalists, and successful bootstrappers alike.
Jason Lemkin’s perspective emphasizes long-term equity preservation:
"If we could answer Yes to all 3 questions, I wouldn’t raise outside capital. It’s so much better, in an ideal world, to skip several rounds of dilution. Especially if you have the time. The extra time it can take if you bootstrap."
Meanwhile, venture capitalists often argue that while bootstrapping is noble, speed to market can be the ultimate competitive moat. In hyper-competitive sectors—such as artificial intelligence or enterprise security—early capital allows companies to blitzscale, lock up enterprise distribution channels, and hire top-tier engineering talent before competitors can catch up.
However, founders who have walked the bootstrapping path offer a stark warning against premature funding. Wade Foster, co-founder and CEO of Zapier—a company that famously raised only a tiny seed round before scaling to massive profitability—has frequently noted that taking too much money too early can distort a company’s culture and force founders to focus on vanity metrics rather than sustainable customer satisfaction. By keeping overhead low and relying on organic adoption, bootstrapped companies retain the ultimate strategic freedom: the ability to build what customers actually want, rather than what investors demand to fit a portfolio thesis.
Implications for Modern Founders
The implications of Lemkin’s insights and the broader bootstrapping movement are profound for the next generation of entrepreneurs navigating a complex economic landscape.
1. The Revaluation of Control
Equity is a founder’s most precious finite resource. Every percentage point diluted away is a slice of future wealth and decision-making authority surrendered. By extending the bootstrapping runway—even by just 12 to 18 months—founders allow their product to mature, customer retention to stabilize, and monthly recurring revenue (MRR) to compound. When they eventually do approach institutional investors, they do so from a position of undeniable strength.
2. Shifting Investor Dynamics
When a startup is desperate for cash, investors hold all the leverage, dictating draconian terms, liquidation preferences, and board control. Conversely, a bootstrapped company with positive cash flow or clear visibility to profitability changes the psychological dynamic of a term sheet negotiation. VCs are forced to compete for allocation, often resulting in cleaner legal structures and higher valuations.
3. Operational Discipline from Day One
Companies forced to be capital-efficient from inception rarely suffer from the bloat that plagues over-funded startups. They focus obsessively on customer acquisition cost (CAC), lifetime value (LTV), and lean product development. Even if a bootstrapped company eventually decides to take venture capital to accelerate its growth, the disciplined operational habits forged during the early months serve as a permanent competitive advantage.
Ultimately, the decision to bootstrap is not about rejecting venture capital entirely; it is about timing. As the entrepreneurial ecosystem matures, the narrative is shifting away from mindless dilution toward strategic patience—proving that sometimes, the fastest way to build a massive company is to take your time at the very beginning.