By The Content Strategy Desk
Published: Industry Insights & Analytics
Executive Summary & Main Facts
In the high-stakes world of financial services marketing, a pervasive paradox exists: the content that fundamentally shapes and wins a high-value deal is frequently created, distributed, and consumed months before the contract is ever signed.
For Chief Marketing Officers (CMOs) and growth leaders in banking, wealth management, insurance, and fintech, this temporal disconnect shatters the utility of traditional Return on Investment (ROI) reporting. Standard, last-touch attribution models—which assign credit exclusively to the final conversion point, such as a contact form or a "Book a Demo" click—are structurally incapable of capturing the nuances of long sales cycles and complex buying committees.
Recent data from leading research firms highlights the severity of this misalignment. According to Gartner, contemporary B2B buying groups range from five to 16 individuals spanning up to four distinct functions. Furthermore, 74% of these buying teams experience internal conflict during the decision-making process as members balance competing departmental goals. Simultaneously, Salesforce data indicates that 57% of sales professionals are experiencing lengthening sales cycles.
When an enterprise finance deal takes up to a year to close—navigated by a sprawling committee of CFOs, risk officers, compliance leads, and analysts—evaluating content through simplistic metrics like page views or single-touch lead gen forms is not just inaccurate; it is an active threat to marketing budgets. To survive budget scrutiny, financial services marketers must abandon antiquated attribution methods and adopt full-journey, multi-stakeholder measurement frameworks that speak the native language of the finance department: risk-adjusted returns, influenced pipeline, and velocity.
The Chronology of a Financial Services Deal: A Case Study in Hidden Influence
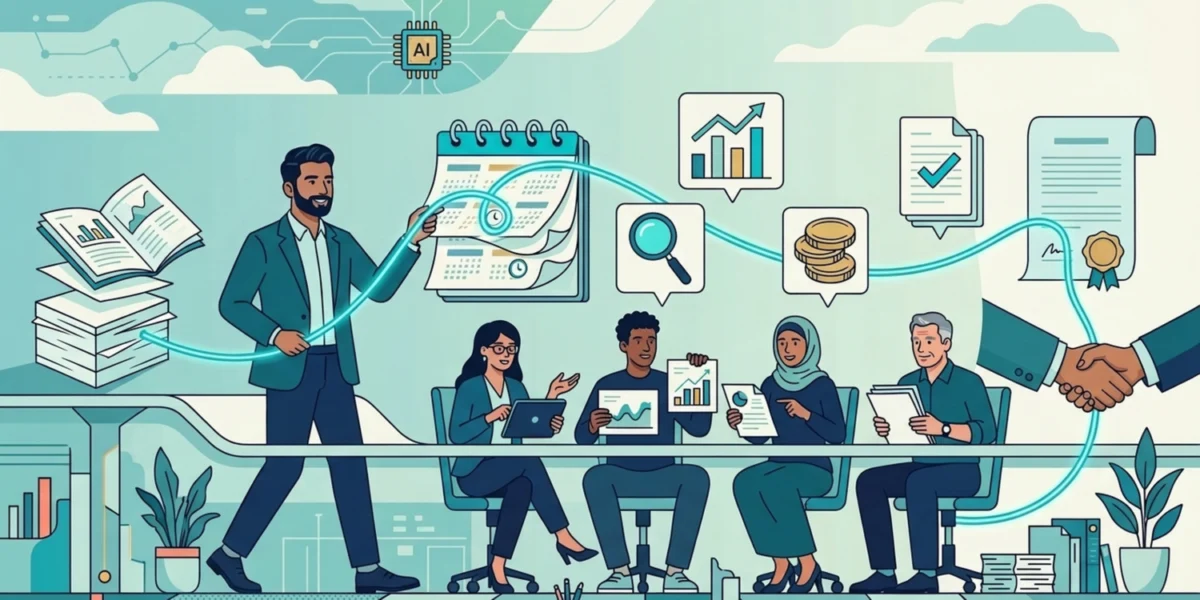
To understand why traditional analytics fail in financial services, one must trace the lifecycle of a modern enterprise finance deal. The journey rarely starts with a direct response ad or a gated white paper submission. Instead, it unfolds across months of quiet, self-directed research, internal debate, and shifting committee dynamics.
Phase 1: The Invisible Discovery (Months 1–3)
In March, an enterprise risk officer at a mid-market institution recognizes a gap in their compliance workflow. Without filling out a form or speaking to a sales representative, they begin conducting self-directed research. According to Gartner, 61% of B2B buyers now explicitly prefer a rep-free buying experience during their evaluation phase.
The risk officer encounters an authoritative, compliance-vetted white paper published by a financial technology vendor. They read it, share it via Slack with an internal analyst, and move on. No lead form is filled. No CRM record is created. Traditional marketing dashboards record zero attribution for this interaction.
Phase 2: Committee Expansion and Internal Friction (Months 4–7)
By June, the initiative gains momentum and formalizes into a project. The buying committee swells to include a controller, an IT security lead, and eventually the Chief Financial Officer (CFO).
As these stakeholders enter the fold, friction mounts. The controller is worried about upfront implementation costs; the IT lead is concerned about data security; the CFO is modeling long-term payback periods. During this phase, the committee independently consumes secondary thought-leadership content—calculators, case studies, and regulatory breakdown guides—provided by the same vendor.
Internal alignment is fraught with tension. Research indicates that nearly three-quarters of buying teams experience active friction due to competing priorities. Content that clarifies regulatory frameworks or models risk mitigation during this window heavily influences the consensus, yet it leaves almost no footprint in standard CRM tracking software.
Phase 3: The Formal Engagement and the Illusion of the Last Touch (Months 8–11)
By October, the committee reaches a consensus. They have effectively made up their minds off-platform. Only now do they officially enter the vendor’s sales funnel. An analyst fills out a bottom-of-funnel form to download a pricing guide or schedule a technical scoping call.
Phase 4: The Close (Month 12)
In November, the contract is signed. When the marketing analytics report is generated at the end of the quarter, last-touch attribution credits 100% of the revenue generated from this multi-million-dollar deal to the generic pricing page download from October.
The months of nurturing, the risk mitigation guides, the CFO-level business cases, and the cross-functional enablement materials are officially rendered invisible by the reporting model.
Supporting Data: The Mechanics of Modern B2B Buying Complexity
The chronological reality of financial services sales is reinforced by robust industry data. Marketers can no longer afford to ignore the structural shifts in how corporate buyers make purchasing decisions.
1. Ballooning Buying Committees
Gartner’s 2025 sales and buying research underscores that modern enterprise deals are collective decisions. A buying group now typically comprises five to 16 stakeholders across multiple organizational silos. In the financial sector, this means a single transaction must satisfy disparate constituencies:
- The CFO/Controller: Focused strictly on capital allocation, predictable cash flow, and cost reduction.
- Risk & Compliance Officers: Focused on regulatory adherence, audit trails, and vulnerability reduction.
- Operations & Analysts: Focused on day-to-day usability, workflow integration, and efficiency gains.
2. Decision-Making Friction
Consensus is rarely smooth. Gartner reports that 74% of B2B buying teams demonstrate unhealthy conflict during the decision process. Financial services buyers are inherently risk-averse; regulatory penalties, compliance missteps, and failed implementations carry catastrophic professional and financial costs. Content that directly resolves these internal conflicts—such as clear regulatory guides, third-party validation, and transparent total cost of ownership (TCO) models—acts as the grease in the wheels of a stalled deal, even if it is never explicitly cited in a sales discovery call.
3. Extended Sales Timelines
Salesforce data confirms that 57% of sales professionals report lengthening sales cycles. In regulated financial sectors, compliance reviews, security audits, and legal redlining routinely stretch deal timelines from months into quarters. As cycles stretch, the number of touchpoints multiplies, diluting the predictive power of first-touch and last-touch attribution models.
Official Responses and Industry Perspectives
As the attribution crisis deepens, revenue leaders, data scientists, and content strategists are sounding the alarm on legacy reporting frameworks.
"For too long, marketing leadership has been forced to defend budgets using metrics that bear zero resemblance to how financial buyers actually buy," notes a senior enterprise marketing director at a global wealth management firm. "When you are selling multi-year treasury management platforms or complex insurance solutions to a committee of ten people, treating a lead form as the ultimate source of truth is professional malpractice."
Financial institutions face an added layer of complexity: regulatory compliance. Content published in the financial sector cannot simply be creative; it must be legally bulletproof. Industry leaders emphasize that the highest-performing content programs rely on credentialed subject matter experts—Chartered Financial Analysts (CFAs), Juris Doctors (JDs), Medical Doctors (MDs), and FINRA-registered reviewers—overseen by rigorous managing editors.
Yet, compliance-approved content often gets buried under archaic analytics frameworks. "We invest heavily in building institutional trust through verified research and expert authorship," explains a fintech Chief Revenue Officer. "When our finance department asks what the ROI is on a white paper reviewed by a FINRA specialist, telling them it generated 40 page views is embarrassing. We need models that capture influence, not just clicks."
Strategic Implications: Building a Full-Journey Measurement Framework
To bridge the gap between months of invisible content consumption and ultimate revenue realization, financial services organizations must execute a systematic overhaul of their measurement and attribution architecture.
1. Shift from Single-Touch to Multi-Stakeholder Attribution
Organizations must retire first-touch and last-touch reporting models. Instead, they should implement multi-touch or weighted attribution models tracked at the account or buying-group level. These models distribute credit across the entire engagement journey, ensuring that early-stage educational assets and mid-funnel risk-mitigation guides receive their rightful share of credit for warming the account.
2. Adopt CFO-Resonant Metrics
To earn the respect of finance leadership, marketing teams must stop reporting on vanity metrics like impressions and raw traffic. Instead, measurement dashboards should prioritize metrics that tie directly to business outcomes:
- Content-Influenced Pipeline: The total value of active pipeline accounts that have engaged with specific content assets.
- Influenced Revenue: Closed-won revenue attributed to accounts that consumed targeted content during their evaluation cycle.
- Buying-Group Reach: A metric measuring how many distinct functional roles (e.g., Risk, Finance, IT) within a target account have interacted with your content library.
- Cycle-Time Impact: An analysis tracking whether accounts that deeply engage with educational and business-case content close faster than those that do not.
- Engagement Depth: Prioritizing quality over quantity—such as time spent interacting with interactive ROI calculators rather than anonymous bounce rates.
3. Triangulate Data via Intent Signals and CRM Integration
Because a significant portion of the financial buying journey occurs off-platform, marketers must build composite visibility. By combining CRM history, marketing automation data, and third-party buyer intent signals (such as G2, Bombora, or direct publisher insights), organizations can approximate the hidden phases of the sales cycle.
4. Align Sales and Marketing Upfront
Before reporting any campaign numbers to the C-suite, sales and marketing leadership must reach an absolute consensus on the attribution model. Disagreements over which touchpoints mattered most undermine credibility during quarterly reviews. A unified model established at the outset ensures that marketing and sales speak with one voice when defending program ROI.
Conclusion
Marketing in financial services will never be as transactional as retail e-commerce or low-end SaaS. The stakes are too high, the committees are too large, and the regulatory hurdles are too steep.
By accepting that a white paper downloaded in March may quietly guide a CFO’s decision in November, financial marketers can liberate themselves from the trap of last-touch attribution. By deploying account-level multi-touch models, focusing on buying-group reach, and speaking the language of risk-adjusted returns and influenced pipeline, marketing leaders can finally demonstrate the true, profound value of their content investments to the most skeptical audience in the corporate hierarchy: the finance department.
Frequently Asked Questions (FAQ)
Why is content ROI significantly harder to measure in financial services than in other industries?
Financial services sales cycles are exceptionally long—often spanning many months—and involve large, cross-functional buying committees. The content that shapes the final purchasing decision is frequently consumed months before a deal closes, often by committee members who never fill out a form or appear in your CRM. Simple, single-touch attribution models completely miss these offline and early-stage interactions.
What attribution model works best for long financial sales cycles?
A multi-touch or weighted attribution model tracked at the account or buying-group level is ideal. This approach credits the entire customer journey—including early educational content, risk-mitigation guides, and C-suite business cases—rather than unfairly handing 100% of the revenue credit to the final form-fill or landing page visited before signing.
Which specific metrics carry the most weight with a CFO?
CFOs evaluate investments based on cost, risk, and return. Metrics that resonate include content-influenced pipeline, influenced revenue, cycle-time impact, and payback period. These metrics translate marketing activity into financial terminology, aligning content performance with how the finance team evaluates every other capital allocation.
How can marketers measure content that buyers consume off-platform or anonymously?
Marketers can approximate hidden engagement by triangulating CRM data, content analytics, and third-party buyer intent signals. By tracking leading indicators—such as engagement depth with interactive financial models and buying-group reach across target accounts—organizations can infer the impact of content during self-directed research phases that no single tracking tool can capture on its own.